






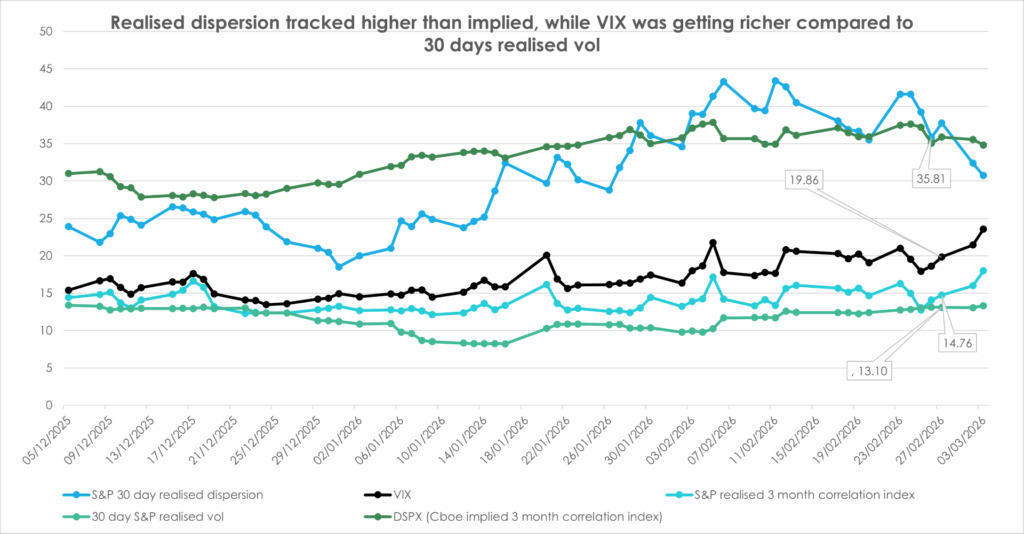
US equity options had been pricing a market built for rotation rather than outright panic. Pre Iran renewed attacks, on 27 February, the S&P 500 30-day realized dispersion index printed 37.75, while the VIX closed at 19.86. At the same time, 3-month implied correlation was 14.76. The market had been pricing for high rotation amid ongoing AI displacements scares.
Dispersion measures how widely individual S&P 500 constituents move relative to each other over a time window. When dispersion is high while implied correlation is low, traders are effectively positioned for a market where winners and losers dissociate, often through sector and factor rotation, even if the index moves themselves look fairly benign, because moves offset.
Carrying index protection had also been expensive in this regime. Using Cboe global market’s VICX as a proxy for 30-day implied S&P 500 volatility and comparing it with 30-day realized volatility from SPX closes, the implied to realized spread was wide going into the “Epic Fury” operation: on 27 February, VIX was 19.86 versus 13.10 for 30-day realized vol. In other words, traders would have been paying up to hedge index tail risks, while dispersion meant portfolios could still see large intra-portfolio moves.
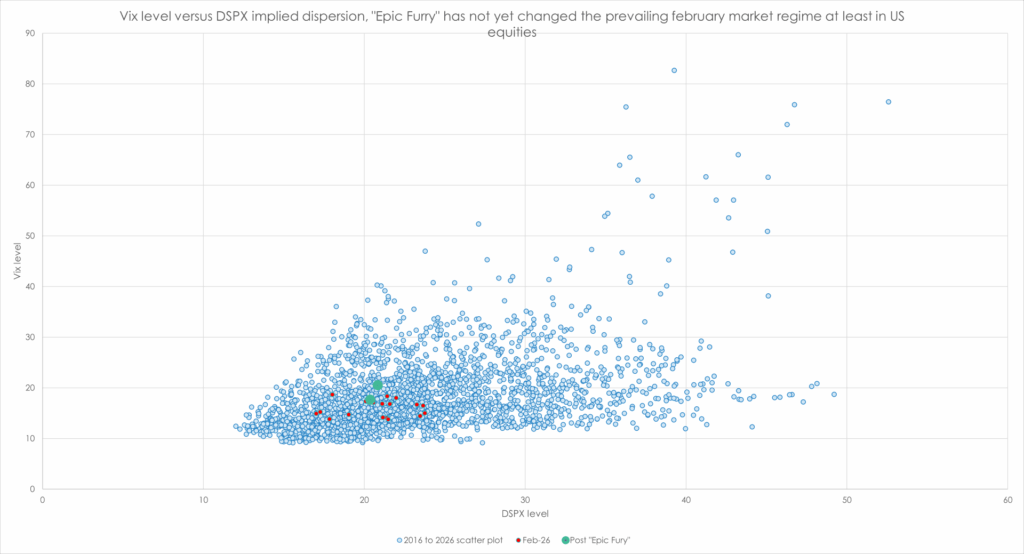
But then the “Epic fury” operation got into gear over the weekend.
In a 2 March note, Cboe’s Mandy Xu wrote: “Oil prices surged higher, up 8% this morning, with tanker traffic in the Strait of Hormuz essentially halted (the Strait handles a fifth of global oil shipments typically).” She added: “Oil 1M implied volatility jumped 7 pts to near a 1-year high of 60% while skew remains extremely inverted (i.e. calls trading at a premium to puts) as investors position for further upside in oil.” Xu also flagged that the upside bid was extending beyond the front end: “we’re seeing this extend to longer-dated options as well, with WTI oil 6M skew also inverting last week – that hasn’t happened since the 2022 Russia/Ukraine conflict.”
By Monday 2 March, in equities, VIX rose to 21.44 and 3-month implied correlation to 16. By Tuesday 3 March, VIX reached 23.57 and implied correlation 17.99. Realized dispersion eased from 37.75 on 27 February to 32.38 (2 March) and 30.73 (3 March).
A long/short hedge fund manager told Traders Magazine: “Markets have somewhat been wrong-footed. As we were all hedging AI perceived dispersion risks, and buying HALO [High asset, Low obsolescence), we did not think we would see such a price shock in emerging or European markets, but index moves have remained subdued in the US.”
Echoing the somewhat peculiar market reactions to the event, Xu noted that amongst haven assets, “US Treasuries, notably, are not [rallying], with bond yields increasing as a result of higher inflation expectations.”
(VOL REPORT is a Traders Magazine – Cboe Global Markets content collaboration that covers volatility and its implications for market participants and operators.)
