






UBS Financial Services (UBS Financial) has been hit with a multi-million U.S Dollar fine from U.S. regulators over anti-money laundering (AML) failures, with authorities citing weaknesses in transaction monitoring, customer due diligence and suspicious activity reporting.
The Financial Crimes Enforcement Network (FinCEN) assessed a $125 million civil money penalty against UBS Financial for willful violations of the Bank Secrecy Act (BSA), marking the largest penalty imposed against a broker-dealer for BSA violations to date.
Separately, the Financial Industry Regulatory Authority (FINRA) fined UBS Financial $20 million for AML violations.
The enforcement actions were announced by FinCEN and FINRA on Monday, August 3, with both regulators citing deficiencies related to transaction monitoring, customer due diligence and the firm’s handling of previously identified AML weaknesses.
“Today’s announcement brings closure to this legacy matter. UBS has cooperated fully with its regulators and has made significant investments to remediate and strengthen its AML program in line with leading industry practices,” a UBS spokesperson said.
Failure to Monitor
According to FinCEN, UBS Financial failed to adequately monitor foreign currency wires and identify potentially suspicious activity, despite having previously entered into a 2018 settlement with the regulator over similar issues.
FinCEN said UBS Financial did not remediate the underlying weaknesses and subsequently failed to appropriately monitor more than 50,000 foreign currency wires with an aggregate value exceeding $10 billion.
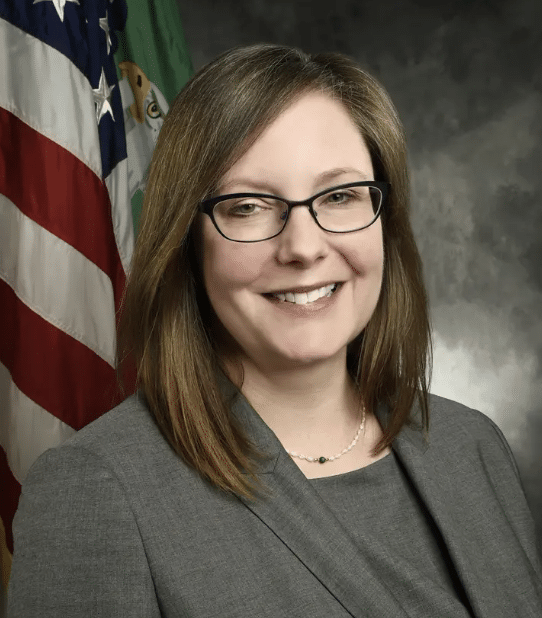
“Today’s historic action against UBSFS should send a clear message that recidivist financial institutions will face severe repercussions,” said FinCEN Director Andrea Gacki.
“Repeat violators of the Bank Secrecy Act jeopardize the integrity of our financial system, especially those that expose it to high-risk customers and activities without effective controls.”
FINRA also found that UBS Financial failed to establish and implement an AML compliance program reasonably designed to detect and report suspicious transactions involving foreign currency wires.
The regulator said UBS Financial continued using a legacy monitoring system after its 2018 settlement. Between January 2019 and January 2021, FINRA said the firm relied on a manual review process that included thousands of foreign currency wire transactions but did not reasonably identify suspicious patterns or incorporate sufficient information about geographic risks.
UBS Financial later implemented an automated transaction monitoring tool in February 2021, but FINRA said data and system issues resulted in additional gaps.
The regulator found that the system omitted a significant percentage of activity, including approximately 33% of foreign currency wires in retail customer accounts approved for foreign currency spot activity.
Between January 2019 and June 2023, UBS Financial failed to reasonably monitor more than 60,000 foreign currency wires totaling more than $10 billion, according to FINRA.
The transactions included activity involving high-risk geographic locations, unusually large transfers, excessive movement of funds, transactions without apparent business purpose and activity involving accounts where suspicious activity reports had previously been filed.
“Member firms operating in global markets bear a responsibility to design and implement AML programs that are tailored to their business model and capable of reasonably monitoring transactions for potentially suspicious activity,” said Bill St. Louis, Executive Vice President and Head of Enforcement at FINRA.
“This action underscores FINRA’s approach to progressive discipline, which includes escalating sanctions for recidivist misconduct,” he added.
Regulators also identified weaknesses in UBS Financial’s customer due diligence processes. FinCEN said the firm failed to appropriately assess and mitigate risks associated with certain high-risk customers, including customers with ties to Russia and Latin America.
The agency said UBS Financial did not sufficiently evaluate factors including source of wealth concerns, adverse media reports and potential links to corruption, fraud and money laundering. As a result, the firm failed to timely identify and report hundreds of suspicious transactions.
FINRA similarly found that UBS Financial did not reasonably implement its customer due diligence program for certain retail customers. The regulator cited failures involving customers’ connections to higher-risk jurisdictions, unexplained changes in domicile and employment, adverse media and potential political exposure.
Madhu Nadig, co-founder and CTO of Flagright, an AI operating system for real-time financial crime compliance, said the case highlights a common weakness in financial institutions’ compliance programs: ongoing reviews of customer risk after onboarding.
“Event-driven review is typically where most compliance programs are weakest and it’s the hardest failure to catch because on the surface, everything looks like it’s working,” Nadig told Traders Magazine.
Flagright is not involved in the UBS case and Nadig spoke as an outside observer.
“Onboarding programs receive the most attention and tooling. But a client’s risk profile is set at inception and then rarely re-underwritten with the same rigor, even as source-of-wealth questions, adverse media or ownership changes accumulate,” he said.
Nadig said FinCEN’s findings reinforce that customer due diligence should extend throughout the life of the client relationship rather than end after onboarding.
“FinCEN was direct that risk-based CDD must run throughout the life of the relationship, not just at the onboarding. That means objectively reassessing risk as it evolves over time; not recording a disposition once and moving on,” he said.
As part of the resolution, UBS Financial will undergo additional reviews of its AML program. FinCEN said the firm will work with a third party to conduct a lookback review to identify suspicious transactions that may have gone undetected due to the compliance failures. The firm will also undergo an independent review focused on addressing the deficiencies identified by regulators.
Nadig said lasting remediation requires more than addressing specific examination findings.
“Regulatory findings get closed on paper faster than the underlying operating model actually changes,” he said. “A firm can remediate every issue an examiner identifies while leaving the underlying conditions untouched.”
He added that firms should focus on whether “the control environment, decision-making authority and incentives have actually changed” and proactively disclose recurring issues rather than waiting for regulators to identify them.
The image for this article was generated using AI.
