







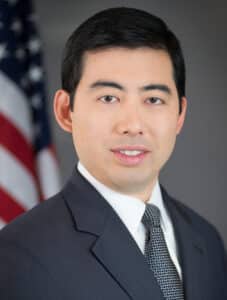
The US Securities and Exchange Commission is considering ways to ease the market transition to the US Treasury central clearing rule, SEC Commissioner Mark Uyeda said Nov. 12 at the Federal Reserve Bank of New York Conference.
The mandate, which was introduced in December 2023, requires hedge funds, banks, and other firms to centrally clear more of their US Treasuries trades through a SEC approved Covered Clearing Agency (CCA). The aim is to improve risk management practices, protect investors and reinforce market resiliency.
Currently, these transactions are either settled bilaterally or cleared centrally through just one CCA, the Fixed Income Clearing Corporation.
Earlier in the year, the SEC announced a year-long delay to implementation in response to market participants’ concerns over the tight deadlines. Under the new timelines, mandatory clearing of eligible Treasury securities cash transactions and Treasury securities repurchase agreement transactions will come into force starting 31 December 2026 and 30 June 2027 respectively.
Uyeda said that SEC is now looking at extending the inter-affiliate exemption to include cash transactions and other types of affiliates. The agency is also exploring how the exclusion could address transactions for internal liquidity and collateral management.
“Many global firms transact heavily among various affiliates for liquidity, collateral management, and hedging purposes,” Uyeda said. “When the Commission adopted the rule, it recognised that the benefits sought by the rule are not realised by subjecting such internal trades to the same requirements as external trades. Therefore, the final Treasury clearing rules contain an exemption for trades between affiliates.”
However, he noted that market participants have stressed that this exemption, as adopted, may be too restrictive to be utilised.
The extraterritorial scope of the Treasury Clearing Rules is also under the microscope. Non-US firms that trade with US counterparties do not typically clear their trades in US Treasury securities, but they may need to establish clearing arrangements with intermediaries or with central counterparties.
The lack of clarity has meant that these firms have not been able to determine their options for clearing access or their costs. Prior to the government shutdown on 1 October, the SEC staff had been engaging with market participants to understand jurisdictional issues.
Other issues raised by the industry include double margining for registered funds regarding cleared repos; cross-margining between securities and futures transactions at the customer level; and the impact of failed trades or clearing agency outages.
Due to the shutdown, discussions have stalled but now that the government is open for business, the pace should accelerate.
“While a lot of progress has been made on the Treasury clearing rules, critical work remains to be completed,” Uyeda said. “The Commission intends to do our part, by providing clarity, guidance, and where appropriate, exemptive relief or rule amendments, so that market participants can proceed with planning and deploying the resources needed to fully implement the Treasury clearing rules.”
