






It’s not easy being a buyside trader these days. Their brokers are less attentive than they used to be. Their portfolio managers are behind the times when it comes to trading. The regulatory environment is becoming more onerous. The marketplace is a mess.
Their World: Day to Day Buyside Concerns
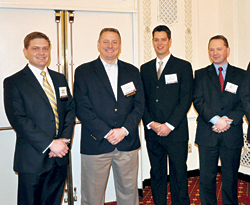
In late January, during the annual conference of the Chicago chapter of the Security Traders Association, a group of four buyside traders from around the Midwest, aired their grievances over a work environment that has changed beyond recognition.
Whereas before they could execute most of their orders in block sizes at a single location, today they must contend with multiple trading spots. Whereas before they could count on their brokers to give them color throughout the day, today the use of instant messaging has eliminated much of that. Whereas before they could count on a plentiful supply of capital, today there is very little.
So just what does the buyside want?
According to the group, their needs are simple: better communication with the sellside, more understanding from their portfolio managers and less fragmentation in the marketplace. Plus half a dozen other things.
The panel vented over such issues as communication, capital, compliance and color. They took their brokers to task, as well as their portfolio managers. They even had words for the vendors in the industry. Traders Magazine was fortunate to be in the audience when the panel held forth on these meat-and-potatoes issues.
The wide-ranging discussion gave the STAC attendee a good picture of life on the buyside trading desk and the pressures and problems faced by the traders.
The outspoken traders included Bob Koci, a 10-year man at Principal Global Investors, who trades micro-caps for the Des Moines, Iowa-based firm.
There was Jeff Nordstrom, who joined Riverbridge Partners in Minneapolis last summer, after spending 11 years across town at Peregrine Capital Management.
Also on the dais was Jeff Pralle of Chicago’s RMB Capital Management, which runs a long-only business as well as a hedge fund, focusing on small- and mid-cap stocks
And finally, there was George Metrou at Chicago’s Perritt Capital Management, a trader of micro-caps.
Their comments are below.
The Telephone
Metrou–We’re old-school. We don’t use Bloomberg or IM. All orders are handled over the phone. You do need to have a hands-on approach with orders. This has been instilled into us by the older guys in our office-the managers and principals of the firm. You talk to your trader over the phone. You have a discussion. We don’t get into a lot of the trading systems. We don’t use that technology.
Pralle–Phone calls are important. You need to establish a relationship. Once you know the broker. Once they know you. Then IMs are invaluable for speed and accuracy. If there is a nuance to the trade, pick up the phone. Don’t leave it to a blank "Buy 10,000 of this, here’s your limit."
Koci–The phone is still the best way to get anything across to anybody. I can’t tell how urgent something is just because you wrote it in caps. To hear your voice. To hear what is going on. To get an idea of how fast the markets are. Or…this is a big opportunity. A liquidity event. Email is at the lower end of the hierarchy. That’s the way you send me written information I can read when I have time. If it is urgent: a phone call first; IM second.
Regarding Vendors
Pralle–I am a one-person shop. I am constantly barraged by vendors. I need less. I need one or two systems on which I can do more and more and more. I don’t want 10 different systems running all at once.
Getting Color in an Electronic Age
Pralle–A lot of the color is largely lost from many, many brokers. They do think that IM…if they are just throwing back a report, that’s good enough. You do miss the color. But a lot of the time on the sellside, the trader simply feels it is adequate to toss back a report and their job is done. And you’re sitting there…I have no idea what you are doing. Because I run both fixed income and equities, my attention is drawn in several different directions. I need someone to be my eyes on the street. To tell me what’s going on. It’s not good enough to just be an order taker. I need to know more.
Metrou–We work specifically in micro-caps-very illiquid names. We have to take a hands-on approach and have that discussion. Please don’t call me with every single IOI. I need a detailed discussion as to how to handle that order. I need to get that feedback throughout the day as to what the trader is seeing in the market, particularly because the stocks we typically trade are very illiquid.
On Transaction Cost Analysis
Koci–We’re all under some guise of TCA. The technology predicts that something should cost 60 basis points without taking into account markets moving one way and your stocks moving in another and all the competition you have. So someone who has never really traded stock is telling you it should cost 60 basis points under these conditions. And you’re trying to trade that. The portfolio manager does not understand anything about liquidity. You could put up a really good trade in block form and still look like an ass at the end of the day compared to the closing price. They’re beholden to a closing price. They don’t care about a print price. None of my PMs care about print prices. Did you buy something lower than it closed? Did you sell it higher than it closed? If you didn’t you look like an ass.
On Splitting Tickets
Koci–Often when I’m in a dark network, I’m sitting with a limit which is usually less liberal than the one I give my broker. The reason is, I don’t want electronic systems out there putting a floor or a ceiling on my name and my brokers always running up against it. So as a result I may be selling something at, say, a nickel with my live broker. But I have a dime limit on my dark system. So the ticket might always look better. But that is actually manipulation. And it is not meant to make me or the electronic system look better. It’s to give my broker enough rope to hang himself, but also enough room to run.
Judging Brokers
Koci–We have situations, especially in our low-liquidity names, where we will have a live agent out there working for us and probably be scraping in the background pools. At end of day, I fill my broker in. They know exactly what I am doing. I tell them I have a piece in the dark. You are working my live portion. I will tell them how they did in comparison, how much they did. I will give them some feedback about what happened and how. Because I consider it a partnership I don’t want to have to fragment my orders. But I have to because I have to go where the liquidity lies. I can’t just give the order to one person to do it all. If I’m not showing performance to my PMs, if they’re not getting something done, it’s reasonable to expect I’m 10 percent or 20 percent or 30 percent of the volume. If I’m not showing that kind of performance, I’m not doing my job. As a result, I have to fragment my tickets. At end of day, it will show that maybe one source did better than the other.
On Market Fragmentation
Nordstrom–You don’t have a choice. You have to go where the liquidity is. I don’t think any buyside trader is a fan of the fragmentation, of being in multiple places at once. Trying to figure out how to allocate the order, how to be fair, etc. If we had a preference, people would much prefer to rein in the fragmentation.
Koci–Everything has become highly fragmented. I prefer an aggregated set-up. Prefer old school. I remember when I came in [in the 1980s] it was three-eighths for 10,000 shares, $15.50. I want to see more de-fragmentation. I want to see more pools of liquidity versus streams of liquidity which we still have a big issue with.
On Portfolio Managers
Nordstrom–In the last year I’ve met with many portfolio managers. There seems to be a disconnect between the PMs’ understanding of what is going on in the trading world: the fragmentation; all the systems. As far as being judged and benchmarked, PMs will still always benchmark you on their understanding of trading 10 years ago versus what is really involved with all the electronics, fragmentation, dark pools, etc. over the last five-plus years. They do look at the closing price. It’s a challenge for all traders to educate PMs.
Decline in Capital Commitment
Koci–I’ve seen a huge decline in capital. I’ve worked at this firm for 10 years. We have been a relatively low user of capital. Still, it never even becomes a conversation now. Used to be something you’d hear all day, every day-somebody offering capital in one spot or another. And it is rare today. You can use your fingers to count how often it happens in a given day. Capital has gone by the wayside in a very large fashion. It’s used for top-tier customers only.
The Morning Call
Metrou–Some of the better emails or calls we get concern the morning flow in our names. That’s obviously very important to us. Everyone is putting pieces together on what’s happening generally in the markets. That’s maybe not as important to me. I don’t need to see all that stuff.
I have newspapers and Bloomberg as well. I can read all that stuff on my own. You don’t need to call me and let me know. I don’t need a call to let me know a press release just came out in a company I own. Thank you. I own the company. I’m well aware they just put out a press release. I don’t need the redundancy. Do your job. The trader provides me with the color of what is going on in the markets in my names. That’s what I can’t access on my own. Flow you’re seeing in the names.
Capitol Hill
Nordstrom–There are a lot of things happening on Capitol Hill that will drive change whether it is the dark pools or ECNs. Who has access, etc. That is where you are going to see change when it comes to technology and how we function in our jobs.
Koci–We have new clients coming in all the time. They are asking for very specific information. Not only about us but the way we conduct our business, including who we are doing it with. Honestly, a lot of these people are a little scared about what’s going on on Capitol Hill right now. As a result they are putting tighter and tighter reins on the way we do our own business.
Role of Compliance
Metrou–There’s definitely more compliance in place over the last couple of years. For me, that means a lot more busy work; a lot more paperwork. It’s a headache. It’s annoying. But I think we all know it’s what we need to be doing.
Pralle–My job has largely been untouched. But I speak quite often with our compliance officer. And she makes me aware of the changes. I plead complete ignorance on many of the minute rule changes. So I rely on my compliance person more than any person to lay it out for me.
Nordstrom–Compliance at Peregrine was on the other side of the building. Now [at Riverbridge] it’s in the same room. It’s 10 feet away. They listen to everything. Their ears perk up: "What’d you say over there?" That’s different. In talking to several buyside shops, you start to see more and more where compliance is getting closer. Whether it’s in the same room or whether they are monitoring trades more through technology. Market stamps are on everything through systems. So they gather the information they want. They’re playing a much more important role.
(c) 2010 Traders Magazine and SourceMedia, Inc. All Rights Reserved.
http://www.tradersmagazine.com http://www.sourcemedia.com/
