






Artificial intelligence is reshaping how investors analyze markets, process information and generate trading ideas, but it may also be creating new inefficiencies and herd behavior in financial markets, according to Osman Ali, global co-head of Quantitative Investment Strategies at Goldman Sachs Asset Management.
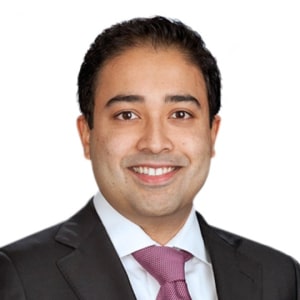
Speaking on the Goldman Sachs Exchanges podcast with hosts Allison Nathan and George Lee, Ali described AI as the latest evolution in a decades-long effort by quantitative investors to extract signals from vast amounts of market data.
Ali’s team, which has been investing quantitatively for roughly 37 years, analyzes around 15,000 stocks daily using a combination of data science, machine learning and AI-driven models. The group operates across public markets and asset classes, seeking what Ali called an “informational edge.”
“AI and machine learning is a big part of how we operate and how we get an informational edge,” Ali said.
He explained that quantitative investing has long relied on models to process data systematically and without emotion. Earlier forms of sentiment analysis, he noted, date back to at least 2008, when the team began using more basic “bag of words” models to gauge investor views on companies.
What has changed, Ali said, is the sophistication of the underlying technology. Large language models and other AI systems can now interpret financial context, detect nuance and work across multiple languages.
“Our team actually takes some of these models and oftentimes it’s not the largest language models, but some of the smaller ones, and fine tunes them,” Ali said, citing Japanese-language sentiment analysis from corporate disclosures as one example.
The goal is to understand how management teams, analysts and investors feel about companies and industries. According to Ali, sentiment and market perception play a larger role in equity returns than many investors assume.
“When we look at equities, more than 50% of what we think drives a stock’s return over the next 12 months is not the fundamentals of the business,” he said. “It is what the market thinks about it.”
Ali argued that modern quantitative investing differs sharply from the early days of the discipline. Decades ago, quantitative teams could process large numbers of securities, but lacked the ability to analyze data deeply. Today, he said, investors can do both.
“The average quantitative investor can be broad … but can you go very deep because the data to do that is available,” he said.
Despite the rapid spread of AI tools, Ali said he does not believe the technology alone guarantees superior performance. Investing, he stressed, remains a “zero sum game,” meaning not everyone can outperform the market.
While generative AI models are becoming widely available, Ali said sustained advantage still depends on proprietary data, infrastructure and experience. Goldman Sachs’ decades-long effort to collect, clean and structure data provides a starting point, he said, but not the entire edge.
“You have to ask the right question to get the informational edge out of these underlying models,” Ali said.
One of the more striking themes from the discussion was Ali’s argument that AI could ultimately make markets less efficient rather than more efficient.
On one hand, he said, AI models may improve price discovery in less-covered areas such as small-cap and emerging-market stocks by helping investors process previously inaccessible information at scale.
But broader use of the same models could also intensify crowding and herd behavior.
“These models, again, in the hands of the average person will create herd behavior,” Ali said. Investors using similar prompts and tools may end up concentrating in the same securities, pushing prices away from fundamentals.
Ali suggested that this dynamic may create new opportunities for investors capable of identifying crowding and reversals.
“If you ask these models the same type of question, they’re going to give you the same type of answer,” he said, arguing that this could make certain market moves more predictable over time.
Lee described that view as “slightly counter consensus,” noting that many observers assume AI should naturally make markets more efficient.
Ali also addressed the impact of AI on staffing within quantitative investing teams. Despite the increasing automation of research and analysis, he said Goldman Sachs Asset Management’s quantitative team has not shrunk materially.
The group remains roughly 100 people globally, he said, though it has grown modestly over time.
“It is absolutely true that a lot of the hard work is done by the machines,” Ali said. “You need to have the right people sitting on top of that.”
He added that investing still requires human judgment, context and experience, even as firms deepen their reliance on data and technology.
For young professionals entering the industry, Ali advised seeking organizations that combine strong investment expertise with serious commitments to data and technology infrastructure.
“There’s also no replacement for experience and context in investing,” he said.
