






DirectMarkets, which links issuers directly with institutional investors, has added three new executive hires and is continuing to expand.
A subsidiary of Rodman & Renshaw, DirectMarkets recently brought on board Jim Feingold, Richard Moore and Matthew Bekerman. It is also looking to hire a new head of marketing.
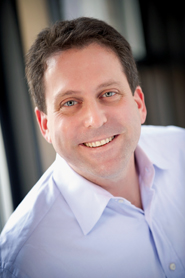
Jim Feingold, a 27-year veteran, joins DirectMarkets as global head of investor sales. He was previously global head of sales and marketing during a five-year stint at execution management system provider Portware.
Kevin Lupowitz, chief executive of DirectMarkets, said Feingold has a tremendous reputation on the Street.
“Jim did some amazing work with Portware,” Lupowitz said. “Being able to get someone like him over to DirectMarkets is a tremendous testament to our business model.”
Before joining Portware, Feingold headed North American sales at Progress Software’s Apama, an algorithmic trading provider. Earlier in his career, he worked at Bloomberg Financial Markets in sales and was a portfolio manager at Laidlaw Capital Management.
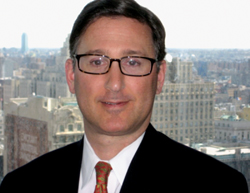
Richard “Rick” Moore is joining the company as director of investor sales. Moore, a veteran of more than 20 years, previously worked with Lupowitz at Merrin Financial. He has also held senior sales positions at Pipeline Trading, Lazard Capital and Instinet.
Lupowitz said he was thrilled when there was an opportunity to bring Moore on board, and that he and Feingold would be a fantastic force together.
Matthew D. Bekerman is now general counsel for DirectMarkets. He was previously assistant general counsel at Liquidnet. Lupowitz called him a technology-savvy lawyer with an amazing breadth of experience.
DirectMarkets is currently filling positions in engineering, operations and relationship management. Lupowitz said the next major hire will be a head of marketing.
The DirectMarkets platform allows issuers and investors to interact and trade with each other directly, thereby eliminating intermediaries like brokers, dark pools and syndicate bankers. Issuers are also permitted to make public transactions if they choose.
“We offer the ability to do ‘at the market’ transactions that will gradually sell primary shares into the secondary market through traditional electronic trading strategies,” Lupowitz said. “The nature of the transaction determines the price and terms of the deal, and whether it is immediately reported or not.”
The goal is to create additional liquidity for investors and larger blocks. Rather than using block trading venues, institutions can send orders directly to the issuer, potentially getting larger blocks than are available through the secondary market.
“The net results are that the proceeds of the sale go right to the company and the institutional customer can get a large block without it adversely affecting its own cost basis,” Lupowitz said.
Issuers pay a subscription fee to be a part of the platform and then Rodman charges users a trading fee, normally between 1 and 2 cents a share for any trades executed.
Not only can issuers sell shares via the system, but they can also repurchase shares in buyback operations. These orders get routed to the R&R sales trading desk, and are executed in the secondary marketplace.
